LIVE ON ZOOM · MONDAYS FROM 12 OCTOBER · £2,199
Forensic Analysis Bootcamp
Ten live sessions on how companies manipulate their accounts, and how to find them in the published numbers.
Instalments available. Most employers will cover the cost, and there is a template below you can send to your manager.
Live on Zoom
Learn directly from an expert
Circle Community
Interact with other students + London Pub Meetup Included
Taken by the world's top Hedge Funds
The Bootcamp covers the same curriculum I deliver to investment teams at Baillie Gifford, Schroders and Wellington, and to a $50bn hedge fund that will not let me name it. The difference is that here I take longer going over it, and you can stop me whenever you like.
Around 200 real examples of accounting tricks, and ten live sessions where the questions are half the point.
“The evidence is usually there. The question is whether you looked.”
10 live Zoom sessions · Mondays from 12 October · Recordings and lifetime access · £2,199
One of our key skills is shorting stocks and identifying accounting issues. Stephen's Behind the Balance Sheet accounting seminars provided a thorough refresher on a number of accounting issues to look for, excellent training to make sure the whole team were comfortable with all the nuances and tricks that corporates use, as well as some more subtle angles that were thought-provoking. The course was carefully put together, combining theory with historic examples of financial shenanigans. An underappreciated topic in the investment world, and Stephen helps to really bring it to life.
More than 1,000 institutional equity and credit analysts and portfolio managers have taken this training.
Taught in London, Edinburgh, Dublin and New York, and on Zoom everywhere from Singapore and Sri Lanka to Sao Paulo and Bermuda. To long-only funds, hedge funds, family offices, credit investors, credit insurers, private equity and quant teams.
Steve talking about fraud, forensic analysis, importance of knowing how to read annual reports and financial statements.
The problem
Most investors obsess over the upside. The damage comes from the other end.
That asymmetry is the reason a lot of good analysis still ends badly, and it costs the two segments of my audience differently.
If you do this professionally, your career lives and dies by the quality of your recommendations. One avoidable blow-up on a name you covered is remembered a great deal longer than a run of good calls.
If you invest your own money, you are probably running a concentrated portfolio. If one position falls seventy per cent, you will feel it in a way an institution never does.
Neither problem is solved by being cleverer about the upside.
And most of the evidence was already published
Thomas Cook's auditors put a going concern reservation in writing. It was not buried at the back. The audit report sits immediately in front of the financial statements, and it was there for anyone who knew why, and how, to read it.
Patisserie Valerie reported revenue of around £114m while carrying roughly £5m of raw materials and consumables. A very similar business with £35m of revenue carried a quarter of a million. Three times the sales, twenty times the inventory. That comparison was sitting in published accounts before the fraud came out, and finding it took one Companies House download.
This did not require a forensic accountant. It needed somebody who knew where to look and had a process for looking there every time.
That is what this is. Not a list of frauds to memorise. A repeatable way of reading a set of accounts that tells you when to stop and when to dig.
Why now
Why this matters more at the end of a cycle than the beginning
After the long bull market of the 1990s there was an explosion of accounting frauds. It started with Enron, and it did not finish with Tyco. This cycle will be no different, and it could be worse.
- Executive compensation now actively encourages manipulation
- Auditors have grown sloppier
- Sell-side research has been juniorised, so there are fewer experienced people asking awkward questions
- Company accounts are considerably more complicated than they were
It will be most prevalent among small caps, as it always is. But large caps are not immune, and I expect some highly rated glamour stocks to be exposed in the next downturn.
Nobody knows when. That is exactly why this is a skill worth having before you need it rather than after.
How it is taught
Why it is not a screening course
There is a well-known indicator of earnings manipulation called the Beneish M-Score. I do not teach you to calculate it. You can get it from Bloomberg or build it in a spreadsheet in an afternoon, and knowing the number tells you almost nothing.
What I teach is why it works. How it is constructed, how it has performed, which companies are currently flagged by it, and then, for every single input, how a company actually manipulates that number in practice.
That is the difference between a screen and a skill. A screen gives you a list. Understanding gives you pattern recognition, which is what lets you see the next one in a company nobody has screened yet.
There is no fluff in this. I get straight to the point, and I do not much care whether certain CFOs would rather I did not.
What an example looks like
Take warranty provisions, which almost nobody looks at.
Compare a company's rolling twelve-month warranty charge in the P&L against its actual cash spend on warranty over the same period. One household name blue chip has twice built provisions well above what it went on to spend, depressing reported margins. More recently it has reversed the position, with the charge running below the cash spend, which boosts earnings.
Neither is fraud. Both change the number you are valuing. Neither is visible if you read the income statement on its own.
There are around 200 examples like that, most of them considerably more involved.
Audience
Who this is for
Equity analysts and portfolio managers — who want to be genuinely good at spotting earnings management, and who know that missing something costs them credibility as well as performance.
Credit analysts and credit investors. — Distress shows up in the balance sheet before it shows up anywhere else, and a large part of this course is about reading exactly that. Multiple credit teams have taken the course and if anything they get more out of it than the equity investors.
Serious private investors — with a reasonable grasp of financial statements who want to analyse companies the way professionals do, because it is their own capital at risk.
Long and short investors, — for whom this is closer to a core skill than a defensive one.
Who this is not for
A warning, meant seriously.
If you do not think good fundamental analysis improves returns, or do not think assessing downside risk is a crucial part of investing, this is not for you, and we will both be happier if you leave it.
It also only works if you are already comfortable with a set of accounts. If you are not yet, you will get far more from my course How To Read A Balance Sheet, and more from this one later.
And there are no shortcuts. Ten weeks, homework, and material you have to apply. People who treat it as a video library do not get much from it.
What you learn
Ten sessions
Most companies using aggressive accounting are not run by crooks. They are run by people with targets, incentives and a strong preference for not disappointing anybody. That is a more common problem than fraud and a more useful one to be able to spot.
The largest category of manipulation and the one with the most methods. Recognition, timing, channel stuffing, related party sales, and what each of them leaves behind in the numbers.
How costs get deferred, reclassified, capitalised, or simply moved somewhere less visible.
Detection systematically rather than case by case, plus how to automate these checks. The longest session in the course and the one people come back to.
How to use AI tools to run these techniques at scale, which parameters and metrics hold up under testing, and where the output still needs a human to check it.
Line by line. Where distress shows up first and earliest.
Properly, rather than the version most people were taught.
The standard textbook test fails more often than people think, and I will show you why.
Management, incentives, disclosure quality, auditor changes, and the things that tell you as much as the numbers do.
What we covered, what matters today, and how to insulate your portfolio.
Outcome
By the end, you will know
- How to modify working capital ratios so they actually detect early revenue recognition and similar manipulation, rather than just describing it
- How cash from operations gets boosted to make a company look more valuable than it is
- How expense capitalisation is used to defer the recognition of liabilities
- Which accounting policy changes flatter earnings, and how to find them
- How expenses are manipulated to boost profits, and occasionally to depress them
- The other ways earnings get temporarily inflated, or simply invented
- The warning signals that accounting quality is deteriorating, before the numbers say so
One thing this is not. It is a course in creative accounting and detecting over-valuation, rather than in conducting a full forensic investigation. I show you the tools short sellers actually use to detect manipulation, and I would rather you could apply seven of those reliably than half remember thirty.
NEW FOR 2026
The 2026 cohort covers the accounting problem nobody has settled yet
Between them, Alphabet, Amazon, Meta and Microsoft have now put $1.5 trillion into fixed assets. Capex has gone from ten per cent of revenue to twenty. Asset intensity is rising at over twenty per cent a year. And reported free cash flow still looks respectable.
Those facts do not sit comfortably together, and working out why is a forensic accounting problem rather than a technology one.
Some of it is simple. Free cash flow takes no account of stock-based compensation, and there is a great deal of it. Some of it is not simple. Last year the increase in the group's gross assets ran roughly $88bn ahead of the cash they actually spent, because assets are increasingly being added on credit rather than bought outright, and the cash flow statement does not show you that.
And Meta moved over $4bn of capex off its own balance sheet into a variable interest entity for its Louisiana data centre, while backstopping the project to the tune of $46bn. That funding is much more expensive than doing it directly, and the structure costs money to set up. The only reason to do it is to flatter the accounts.
None of this is a new technique. They are old techniques applied to the largest numbers in the market, which is exactly why it is worth understanding how to analyse them.
Dates
Ten Mondays
| Session | Date | Topic |
|---|---|---|
| 1 | 12 October | Introduction: why companies cheat |
| 2 | 19 October | Cheating 1: revenue |
| 3 | 26 October | Cheating 2: expenses and the P&L |
| 4 | 2 November | Accounting red flags |
| 5 | 9 November | Technicals: applying AI |
| 6 | 16 November | The balance sheet |
| 7 | 23 November | The P&L |
| 8 | 30 November | The cash flow statement |
| 9 | 7 December | Soft factors |
| 10 | 14 December | Round-up |
- 12 October
- Introduction: why companies cheat
- 19 October
- Cheating 1: revenue
- 26 October
- Cheating 2: expenses and the P&L
- 2 November
- Accounting red flags
- 9 November
- Technicals: applying AI
- 16 November
- The balance sheet
- 23 November
- The P&L
- 30 November
- The cash flow statement
- 7 December
- Soft factors
- 14 December
- Round-up
Sessions run from 6pm UK time, which is 1pm in New York. Around 60 minutes of teaching, usually 90 with questions, and longer if the questions deserve it. All recorded.
Instructor
Who is teaching it
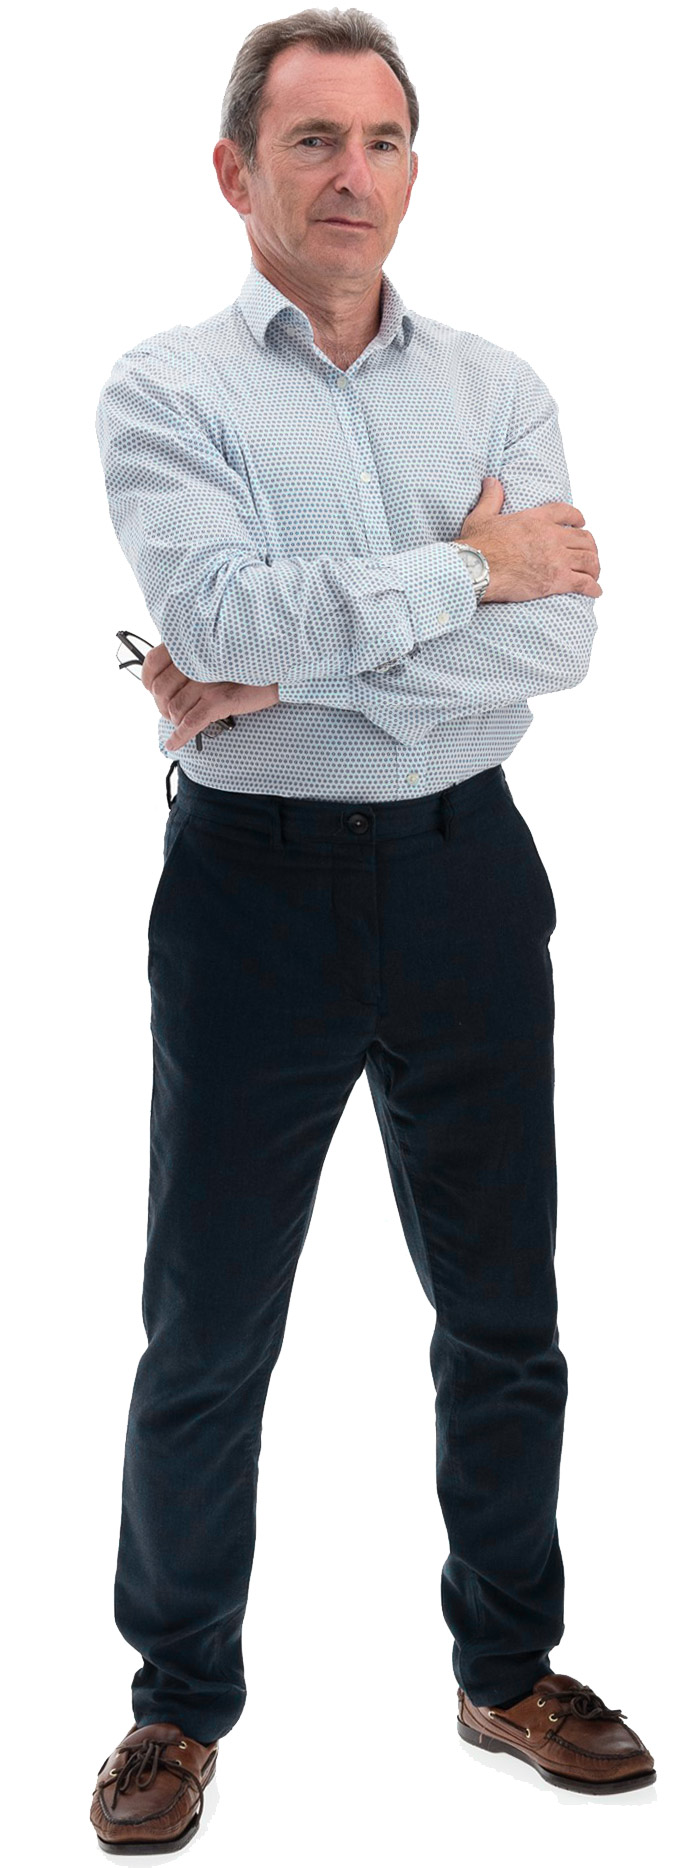
I am Stephen Clapham. I was a partner and head of research at two multi-billion-dollar hedge funds, one of them a Tiger Cub.
I got there the long way. Thirty years, starting on the sell side covering transport, then across to the buy side.
In 2018 I started Behind the Balance Sheet, because the way I had learned to read accounts was not written down anywhere and it should have been. Since then I have taught teams at institutions like Baillie Gifford, Schroders and Wellington, and a number of hedge funds that would rather I did not say so, because they treat this as an edge and would prefer their competitors did not have it.
I wrote The Smart Money Method. I write about accounting on Substack most weeks. This is the sixth time I have run the Bootcamp.
You could spend thirty years working this out for yourself, as I did. Or you could have ten Monday evenings.
Steve talking about fraud, forensic analysis, importance of knowing how to read annual reports and financial statements.
What is included
What you get
- Ten live sessions with me on Zoom, so you can join from anywhere
- Full recordings of every session
- Lifetime access, including the material from all five previous cohorts
- Direct access to me and to the other students throughout
- Supporting material and exercises, so you apply each session rather than just watch it
- A free bonus session from a guest speaker at the end of the course. Past presenters include Russell Napier and Pulak Prasad
- Free access to my online course How To Read A Balance Sheet, worth £399
- Limited places, so the group stays small enough to be useful
The room
A small group, on purpose
Places are limited deliberately. Ten sessions with a group small enough that people get to know each other is a different experience from ten sessions with an audience.
I did not expect this to be the part people mention most, but it is. Investing is solitary. Most people reading this spend a lot of time alone with a spreadsheet and an annual report and nobody to ask whether something looks odd. For ten weeks there is somebody, and previous cohorts are in the community too.
If you are in London, we meet in a pub from time to time, so you can meet your own cohort and people from previous ones. The next is in November.
Enrolment
£2,199
Ten sessions, starting Monday 12 October.
Three instalment option available. Dollar pricing available.
Ten sessions, finishing 14 December. Places are limited.
Ask your employer first
Most people asking about the Bootcamp are weighing up £2,199 of their own money, and a good number of them do not need to.
Plenty of asset managers spend enormous sums on the research team while the training budget goes only partly deployed. This is precisely what that budget is for, and research skills can be learned, honed and advanced at a relatively limited cost by comparison. I deliver a version of this course to teams at many of the largest institutional investors, so it is not a difficult case to make.
There is a template below you can send to your manager. It takes about two minutes.
Bringing colleagues
Most of my work is with investment teams rather than individuals, and there is a reason firms do it that way. When a team learns this together, everybody is working to the same standard, and you can apply it to live positions in the portfolio while the course is still running.
For three or more people from the same firm, get in touch at info@behindthebalancesheet.com and I will sort out a discounted group rate.
Logistics
Format and schedule
- Delivery
- Live on Zoom. Ten sessions, Mondays at 6pm UK time, 1pm in New York. Every session recorded.
- Duration
- Ten weeks. Around 60 minutes of teaching per session, usually 90 with questions, and longer if the questions deserve it.
- Dates
- Monday 12 October to Monday 14 December 2026, weekly.
- Group size
- Limited deliberately, so the group stays small enough that everyone can ask questions and take part.
- Materials
- Full recordings of every session and lifetime access, including the material from all five previous cohorts. Supporting exercises for each session. Free access to How To Read A Balance Sheet, worth £399. A bonus guest session at the end of the course.
References
What participants say
Steve's course is a detailed and timely reminder of the importance of looking at the accounts and what might lie beneath the headline numbers. You will learn a lot, be able to challenge and question companies more, and make better-informed investment decisions.
It is our job to avoid the portfolio torpedoes at all costs, which come from poor accounting. Our team's discussions continued long after Steve's departure.
In this business, you meet a lot of people. Whenever I see Steve, it's a seal of approval. I have a lot of respect for him.
Can thoroughly endorse Steve Clapham's Forensic Analysis Bootcamp. The manner in which Steve systematically dissects a set of accounts is very insightful. Even those analysts and PMs with a good grounding in accounts analysis will benefit from attending this course.
I spent more than 15 years as a sell-side analyst, and I wish I had done Steve's course at the start of my career. In fact, it should be mandatory for anyone responsible for analysing companies and their accounts.
As a non-finance professional, I never realised how many ways and how subtly management could manipulate the financial statements. I view a 10-K quite differently from before.
- The Times
Steve has written a regular column for Investors Chronicle, has appeared multiple times on Radio 4's Today programme and on Real Vision, and his newsletter is regularly featured in the FT's reading list.
Questions
Frequently asked
Monday 12 October 2026, then weekly for ten weeks, finishing 14 December. Full dates above.
6pm UK time, which is 1pm in New York. One exception for those in the US. UK clocks change on 25 October and American clocks a week later, so the session on 26 October falls at 2pm New York time rather than 1pm. Every other week is 1pm.
Around 60 minutes of teaching, usually 90 with questions, and longer if the questions deserve it.
I recommend attending live, because the questions and interaction are half the value. Full recordings of every session are available if you cannot.
Lifetime, on any devices you own, including the material from previous cohorts.
Very often, yes. There is a reimbursement template above.
Yes. Three payments, for a modest extra cost.
Yes, for three or more from the same firm. See above.
I do not recommend it, but I understand it is difficult for students in Asia. There is a discounted rate, so ask and I will send a code. I do not recommend this for other time zones.
Ten sessions. Starts 12 October.
£2,199. Ten sessions, starting 12 October. Places are limited.